
Ohio House passes bill rounding government cash payments to nearest nickel
Legislation sponsored by Rep. Bill Roemer and Rep. Thomas Hall would set cash rounding rules and shield merchants from liability, following passage in the Ohio House.
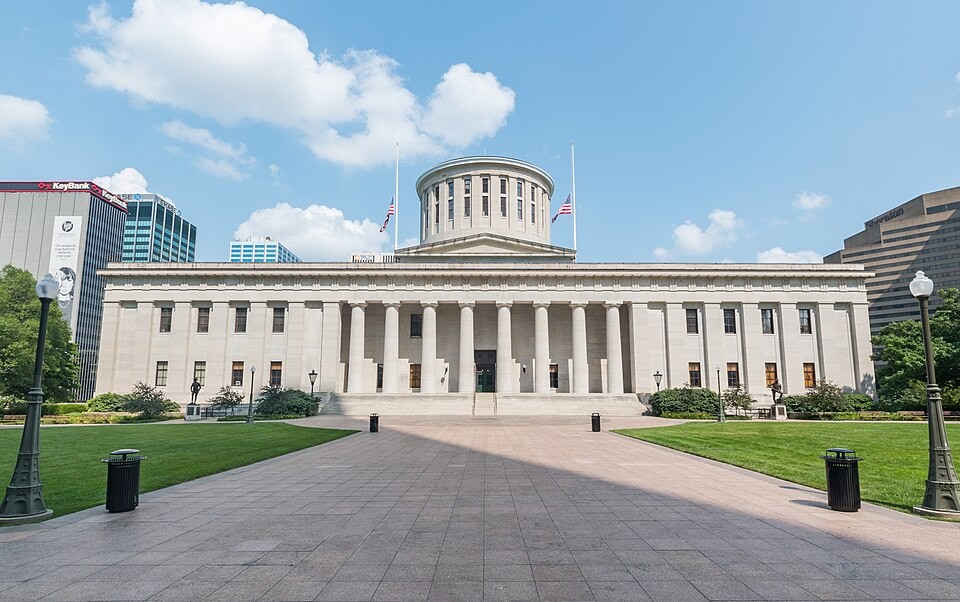
The Ohio Statehouse in downtown Columbus, seat of the Ohio General Assembly.
Credit: Ɱ via Wikimedia Commons Image source
On Wednesday, Nov. 18, the Ohio House of Representatives approved Substitute House Bill 737 on a 70-21 floor vote. The measure would require that cash payments made to state and local government entities be rounded to the nearest nickel. Primary sponsors for the legislation are Rep. Bill Roemer (R-House District 31) and Rep. Thomas Hall (R-House District 46), according to legislative records and caucus announcements.
Under the bill, any person who directly pays any tax, toll, fee, fine, or other charge to the state, a state agency, or a political subdivision in cash—except taxes and fees administered by the tax commissioner—is required to round the payment to the nearest five cents, and the receiving government entity must accept the rounded total as payment in full. Under the statutory rules, amounts in which the second decimal place is 1 or 2 are rounded down so that place is 0, except that amounts in which the second decimal place is 1 or 2 and all preceding digits are 0 are rounded up so that place is 5. Amounts in which the second decimal place is 3 or 4 are rounded up to 5, amounts in which the second decimal place is 6 or 7 are rounded down to 5, and amounts in which the second decimal place is 8 or 9 are rounded up to 0.
The measure also permits a merchant who accepts cash payments to round the final price under those statutory rules, providing that merchants shall incur no liability for doing so when the rounding follows the calculations in the statute. For cash transactions subject to a tax or fee levied by the state or a political subdivision, a merchant may still round the final price, but that adjustment does not alter the tax or fee remitted to the government.
The bill also amends section 321.261 of the Revised Code to address rounding differences in cash payments for real-property and manufactured-home taxes, directing how those amounts interact with a county treasurer's delinquent tax and assessment collection fund. According to official legislative documents, no local impact statement procedure was required because the bill imposes no local cost.
Official legislative records show the bill as passed by the House, while its introduction in the Senate was not marked as completed as of Thursday morning.
Video Watch video 0:29
Pique’s reporting on the same events, newest first.
Ohio Latest
Ohio House votes 86-0 to concur on recovery housing certificate bill
The bipartisan measure cleared both chambers without opposition, with official records showing concurrence recorded but no enrolled bill or presentment to the governor.
Ohio
Ohio House votes 1-85 against Senate changes to School Bus Safety Act
The Ohio House voted 1-85 not to concur in the Senate's changes to Sub. H.B. 3, the School Bus Safety Act; the bill remains in the legislature.
Ohio
Ohio House approves bill to show tax rates as true-value percentage
The legislation would also require ballot language for local income-tax levies to disclose estimated annual revenue.
Ohio
Ohio Senate Concurs in Freedom to Carry Bill Allowing Damages for Local Gun Controls
Official legislative records show no enrolled version listed for the bill sponsored by Sen. Terry Johnson following House and Senate approval.
Ohio You are reading
Ohio House passes bill rounding government cash payments to nearest nickel
Ohio
Ohio House Passes Juvenile Employment Qualification Certificate Measure in 92-0 Vote
The bipartisan bill would create court-issued employment certificates for 17-year-olds with delinquency records, would provide specified employer immunity, and would bar specified wage discrimination.
How we know this
The sources and records behind this story, with the facts they support.
Ohio House Journal, Wednesday, Nov. 18, 2026, official PDF; observed Nov. 19, 2026, ~10:47 a.m. ET
Supporting evidence (1)
On Wednesday, Nov. 18, the Ohio House of Representatives approved Substitute House Bill 737 on a 70-21 floor vote.
Read supporting passage
Records that Sub. H.B. 737 was taken up for third consideration, that the yeas and nays resulted yeas 70, nays 21, and 'The bill passed.'
Supporting evidence (3)
The measure would require that cash payments made to state and local government entities be rounded to the nearest nickel.
Read supporting passage
to amend section 321.261 and to enact section 9.18 of the Revised Code to require that cash payments to the state and local governments be rounded to the nearest nickel.
Primary sponsors for the legislation are Rep. Bill Roemer (R-House District 31) and Rep. Thomas Hall (R-House District 46), according to legislative records and caucus announcements.
Read supporting passage
Primary sponsors listed as Bill Roemer and Thomas Hall.
Official legislative records show the bill as passed by the House, while its introduction in the Senate was not marked as completed as of Thursday morning.
Read supporting passage
The status graphic showed Passed By House; Introduced In Senate was not marked as completed on this observation.
https://www.ohiohouse.gov/members/bill-roemer
Supporting evidence (1)
Primary sponsors for the legislation are Rep. Bill Roemer (R-House District 31) and Rep. Thomas Hall (R-House District 46), according to legislative records and caucus announcements.
Read supporting passage
Representative Bill Roemer - District 31
https://www.ohiohouse.gov/members/thomas-hall
Supporting evidence (1)
Primary sponsors for the legislation are Rep. Bill Roemer (R-House District 31) and Rep. Thomas Hall (R-House District 46), according to legislative records and caucus announcements.
Read supporting passage
Representative Thomas Hall - District 46
Supporting evidence (1)
Primary sponsors for the legislation are Rep. Bill Roemer (R-House District 31) and Rep. Thomas Hall (R-House District 46), according to legislative records and caucus announcements.
Read supporting passage
State Representatives Bill Roemer (R-Richfield) and Thomas Hall (R-Madison Twp.) have introduced House Bill 737
Supporting evidence (1)
Under the bill, any person who directly pays any tax, toll, fee, fine, or other charge to the state, a state agency, or a political subdivision in cash—except taxes and fees administered by the tax commissioner—is required to round the payment to the nearest five cents, and the receiving government entity must accept the rounded total as payment in full.
Read supporting passage
(B) Except taxes and fees administered by the tax commissioner, any person who directly pays any tax, toll, fee, fine, or other charge to the state, a state agency, or a political subdivision, in cash, shall round the payment amount
Supporting evidence (8)
Under the bill, any person who directly pays any tax, toll, fee, fine, or other charge to the state, a state agency, or a political subdivision in cash—except taxes and fees administered by the tax commissioner—is required to round the payment to the nearest five cents, and the receiving government entity must accept the rounded total as payment in full.
Read supporting passage
to the nearest five cents, and the state, state agency, or political subdivision shall accept the rounded amount as payment in full, as follows:
Under the statutory rules, amounts in which the second decimal place is 1 or 2 are rounded down so that place is 0, except that amounts in which the second decimal place is 1 or 2 and all preceding digits are 0 are rounded up so that place is 5.
Read supporting passage
(1)(a) Subject to division (B)(1)(b) of this section, amounts in which the second decimal place is "1" or "2" shall be rounded down to an amount in which the second decimal place is "0."
Under the statutory rules, amounts in which the second decimal place is 1 or 2 are rounded down so that place is 0, except that amounts in which the second decimal place is 1 or 2 and all preceding digits are 0 are rounded up so that place is 5.
Read supporting passage
(b) Amounts in which second decimal place is "1" or "2" and all preceding digits are "0" shall be rounded up to an amount in which the second decimal place is "5."
Amounts in which the second decimal place is 3 or 4 are rounded up to 5, amounts in which the second decimal place is 6 or 7 are rounded down to 5, and amounts in which the second decimal place is 8 or 9 are rounded up to 0.
Read supporting passage
(2) Amounts in which the second decimal place is "3" or "4" shall be rounded up to an amount in which the second decimal place is "5."
Amounts in which the second decimal place is 3 or 4 are rounded up to 5, amounts in which the second decimal place is 6 or 7 are rounded down to 5, and amounts in which the second decimal place is 8 or 9 are rounded up to 0.
Read supporting passage
(3) Amounts in which the second decimal place is "6" or "7" shall be rounded down to an amount in which the second decimal place is "5."
Amounts in which the second decimal place is 3 or 4 are rounded up to 5, amounts in which the second decimal place is 6 or 7 are rounded down to 5, and amounts in which the second decimal place is 8 or 9 are rounded up to 0.
Read supporting passage
(4) Amounts in which the second decimal place is "8" or "9" shall be rounded up to an amount in which the second decimal place is "0."
The measure also permits a merchant who accepts cash payments to round the final price under those statutory rules, providing that merchants shall incur no liability for doing so when the rounding follows the calculations in the statute.
Read supporting passage
Merchants who round the final price of cash payments in accordance with the calculations described in division (B) of this section shall incur no liability for doing so, notwithstanding any contrary provision of the Revised Code.
For cash transactions subject to a tax or fee levied by the state or a political subdivision, a merchant may still round the final price, but that adjustment does not alter the tax or fee remitted to the government.
Read supporting passage
If the cash payment to the merchant is for a transaction subject to a tax or fee levied by a political subdivision or the state, then the merchant may round the final price as described in division (B) of this section. Any
Supporting evidence (1)
For cash transactions subject to a tax or fee levied by the state or a political subdivision, a merchant may still round the final price, but that adjustment does not alter the tax or fee remitted to the government.
Read supporting passage
adjustments made as a result of that rounding shall not change the amount of the tax or fee the merchant remits to the political subdivision or the state.
H.B. 737 As Passed by the House official PDF; observed Nov. 19, 2026, ~10:51 a.m. ET
Supporting evidence (1)
The bill also amends section 321.261 of the Revised Code to address rounding differences in cash payments for real-property and manufactured-home taxes, directing how those amounts interact with a county treasurer's delinquent tax and assessment collection fund.
Read supporting passage
Amends R.C. 321.261 regarding rounding differences in real-property and manufactured-home tax cash payments and the county treasurer's delinquent tax and assessment collection fund.
Ohio Legislature H.B. 737 documents page; observed Nov. 19, 2026, ~10:51 a.m. ET
Supporting evidence (1)
According to official legislative documents, no local impact statement procedure was required because the bill imposes no local cost.
Read supporting passage
Official documents page lists legislation text versions and lists Analysis and Fiscal Notes. Local Impact Statement Procedure Required: No — No local cost.