
Ohio Attorney General Clarifies County GIS Authority and Tax Map Duties
A formal opinion concludes county engineers do not hold exclusive control over GIS systems, while preserving their sole duty over tax maps.
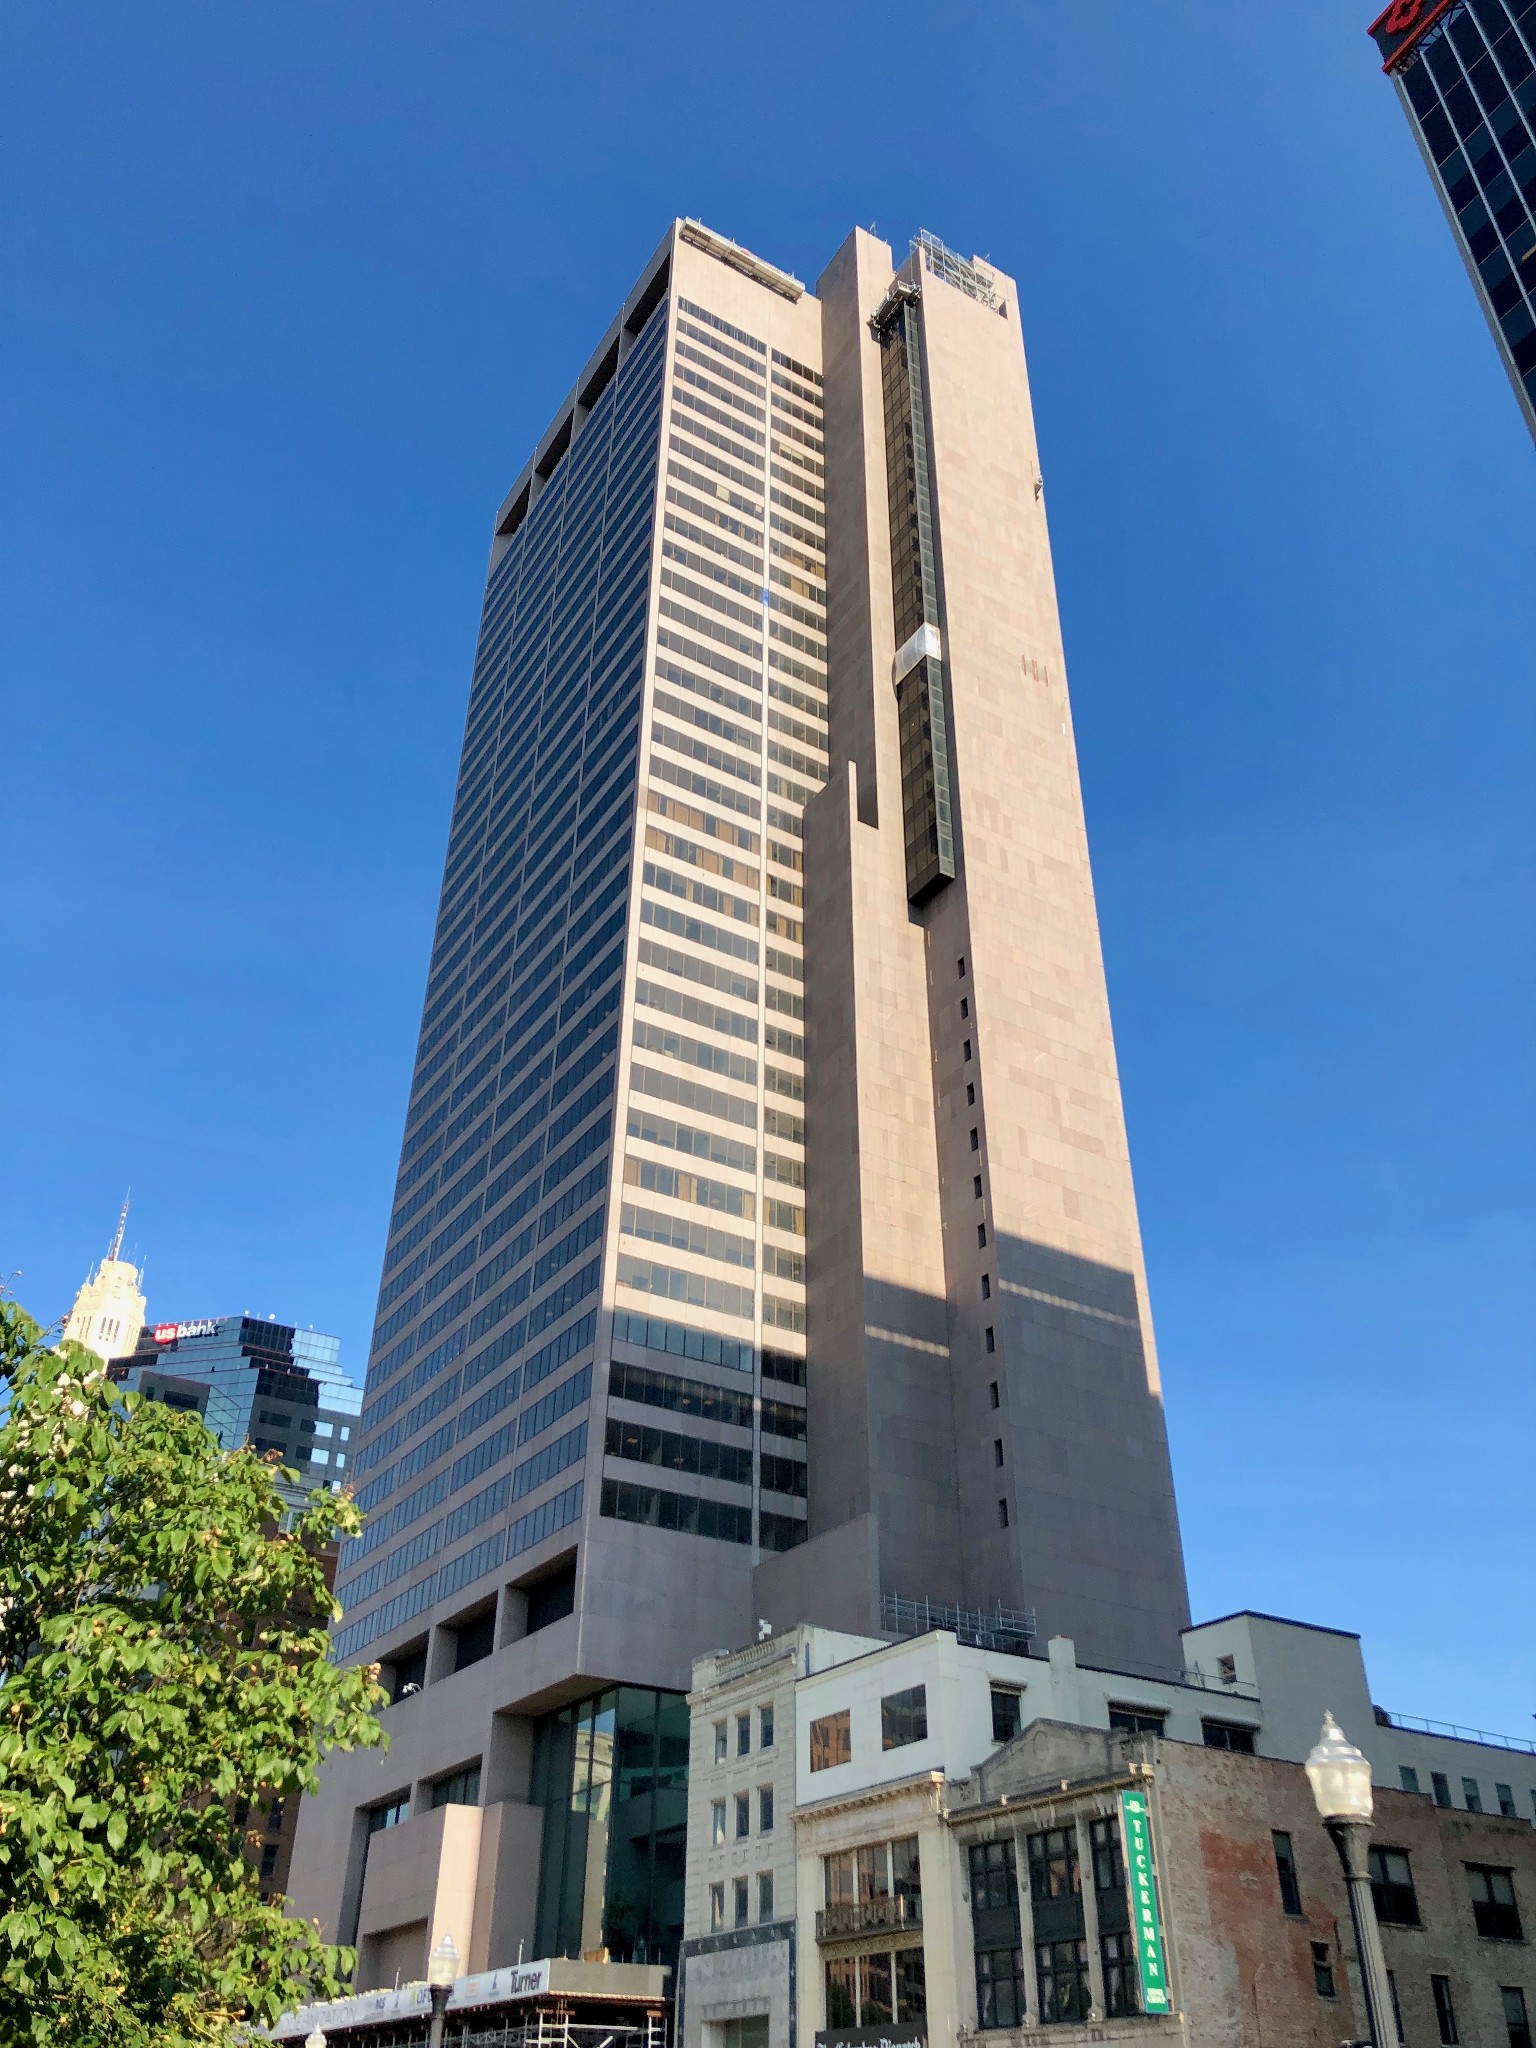
The Rhodes State Office Tower in downtown Columbus houses the Ohio Attorney General's Office.
Credit: w_lemay / Wikimedia Commons Image source https://creativecommons.org/publicdomain/zero/1.0/
On Nov. 16, 2026, Ohio Attorney General D. Andrew Wilson issued formal Opinion No. 2026-012 to Trumbull County Prosecuting Attorney Dennis Watkins. In the opinion, Wilson concluded that a county engineer is not entitled to exclusive control of a county's geographic information systems technology.
Wilson also concluded that only the county engineer may create, maintain, and update county tax maps. The Ohio Attorney General's formal opinions list included Opinion No. 2026-012 on Nov. 19, 2026.
The opinion interprets state statutes, R.C. 5713.09 and R.C. 325.31, that apply to county engineers and auditors.
A county engineer's statutory duty to prepare, maintain, and update the county's tax maps does not extend to all GIS-related mapping performed by the county. The engineer's tax map department may operate concurrently with GIS units maintained by the county auditor or other county offices, provided no office interferes with another's statutory duties.
Under the second syllabus point, each county office may use GIS technology to fulfill its own statutory responsibilities, but only the county engineer may create, correct, or update the county's tax map as defined in Section 5713.09 of the Ohio Revised Code.
Although R.C. 5713.09 does not specify how tax maps must be provided to the county auditor, the tax maps are created and maintained for the use of the county board of revision and the auditor. Therefore, the county engineer must furnish tax maps to the county auditor in a format that enables the auditor to readily perform statutory functions, including GIS-based appraisal activities.
The opinion also addresses which county offices may pay for mapping work from the real estate assessment fund. Under the fourth syllabus point, a county engineer's GIS-related costs may not be paid from the real estate assessment fund. The real estate assessment fund may be used only for expenses incurred by the county auditor or the county board of revision, including the auditor's costs of acquiring or using GIS.
Under the fifth syllabus point, a county auditor's authority under R.C. 325.31(B)(4) to use the real estate assessment fund for GIS and mapping technologies does not authorize the auditor to alter or correct tax-map layers the engineer is required to maintain under R.C. 5713.09. However, the auditor "may add appraisal-related GIS layers that do not disturb the engineer's tax-map content."
Video Watch video 0:40
How we know this
The sources and records behind this story, with the facts they support.
Syllabus text of Opinion 2026-012 as captured from the official PDF, Nov. 19, 2026, ~12:57 p.m. ET
Supporting evidence (13)
On Nov. 16, 2026, Ohio Attorney General D. Andrew Wilson issued formal Opinion No. 2026-012 to Trumbull County Prosecuting Attorney Dennis Watkins.
Read supporting passage
Dated November 16, 2026. Addressed to The Honorable Dennis Watkins, Trumbull County Prosecuting Attorney, Warren, Ohio. Signed: D. ANDREW WILSON, Ohio Attorney General.
In the opinion, Wilson concluded that a county engineer is not entitled to exclusive control of a county's geographic information systems technology.
Read supporting passage
For the reasons that follow, I conclude the county engineer is not entitled to exclusive control of the county's GIS technology. Only the engineer may create, maintain, and update the county tax maps.
Wilson also concluded that only the county engineer may create, maintain, and update county tax maps.
Read supporting passage
For the reasons that follow, I conclude the county engineer is not entitled to exclusive control of the county's GIS technology. Only the engineer may create, maintain, and update the county tax maps.
A county engineer's statutory duty to prepare, maintain, and update the county's tax maps does not extend to all GIS-related mapping performed by the county.
The engineer's tax map department may operate concurrently with GIS units maintained by the county auditor or other county offices, provided no office interferes with another's statutory duties.
Under the second syllabus point, each county office may use GIS technology to fulfill its own statutory responsibilities, but only the county engineer may create, correct, or update the county's tax map as defined in Section 5713.09 of the Ohio Revised Code.
Read supporting passage
Each county office may use GIS technology to fulfill its own statutory responsibilities, but only the county engineer may create, correct, or update the county's tax map as defined in R.C. 5713.09.
Although R.C. 5713.09 does not specify how tax maps must be provided to the county auditor, the tax maps are created and maintained for the use of the county board of revision and the auditor.
Read supporting passage
Although R.C. 5713.09 does not specify how tax maps must be provided to the county auditor, the tax maps are created and maintained
Although R.C. 5713.09 does not specify how tax maps must be provided to the county auditor, the tax maps are created and maintained for the use of the county board of revision and the auditor.
Read supporting passage
for the use of the county board of revision and the auditor.
Therefore, the county engineer must furnish tax maps to the county auditor in a format that enables the auditor to readily perform statutory functions, including GIS-based appraisal activities.
Read supporting passage
Therefore, the county engineer must furnish them to the county auditor in a format that enables the auditor to readily perform the office's statutory functions, including GIS-based appraisal activities.
Under the fourth syllabus point, a county engineer's GIS-related costs may not be paid from the real estate assessment fund.
Read supporting passage
The county engineer's GIS-related costs may not be paid from the real estate assessment fund.
The real estate assessment fund may be used only for expenses incurred by the county auditor or the county board of revision, including the auditor's costs of acquiring or using GIS.
Read supporting passage
That fund may be used only for expenses incurred by the county auditor or the county board of revision, including the auditor's costs of acquiring or using GIS.
Under the fifth syllabus point, a county auditor's authority under R.C. 325.31(B)(4) to use the real estate assessment fund for GIS and mapping technologies does not authorize the auditor to alter or correct tax-map layers the engineer is required to maintain under R.C. 5713.09.
Read supporting passage
The county auditor's authority under R.C. 325.31(B)(4) to use the real estate assessment fund for GIS and mapping technologies does not authorize the auditor to alter or correct the tax-map layers the engineer is required to maintain under R.C. 5713.09.
However, the auditor "may add appraisal-related GIS layers that do not disturb the engineer's tax-map content."
Read supporting passage
However, the auditor may add appraisal-related GIS layers that do not disturb the engineer's tax-map content.
Supporting evidence (1)
The Ohio Attorney General's formal opinions list included Opinion No. 2026-012 on Nov. 19, 2026.
Read supporting passage
Ohio Attorney General formal opinions list (2026-012 listed first); observed Nov. 19, 2026, ~12:55 p.m. ET