Gahanna Halves Income Tax Growth Forecast as Remote Work Squeezes Capital Plan
A projected $3.6 million municipal revenue decline leaves Creekside flood mitigation unfunded for 2027, echoing suburban withholding strains across Central Ohio.
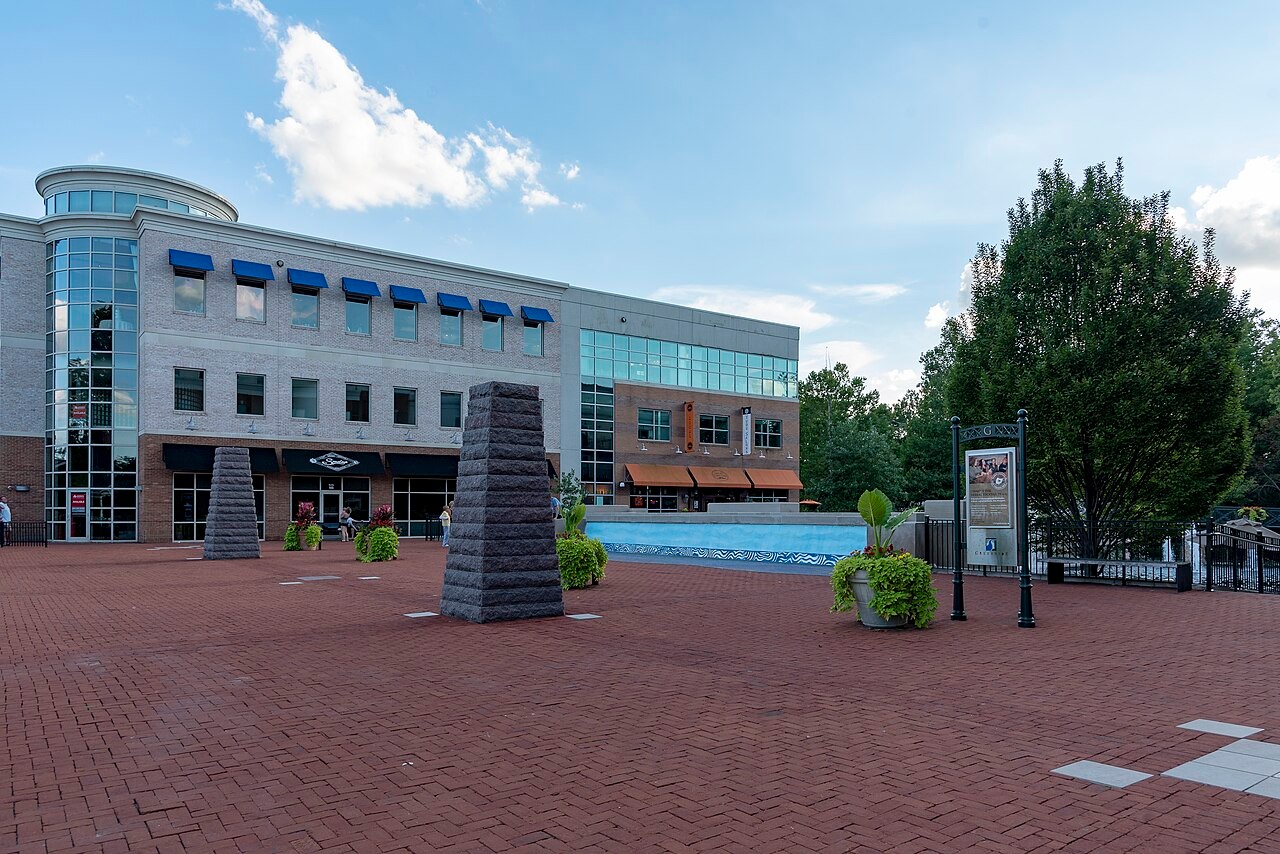
Gahanna City Council is reviewing a trimmed five-year capital improvement program after municipal finance leaders halved projected annual income tax growth from 4% to 2%, citing persistent shifts to remote and hybrid employment.
The downgrade, incorporated into Ordinance ORD-0038-2026 introduced on first reading on Oct. 5, eliminates an estimated $3.6 million in anticipated revenue across income-tax-supported municipal accounts over the planning cycle, according to administrative presentations. The reduction removes approximately $1.1 million directly from Gahanna's Capital Improvement Fund, leaving a signature $23 million to $24 million flood mitigation and plaza renovation project at Creekside without municipal funding for 2027.
The fiscal retrenchment highlights how post-pandemic work arrangements continue to reshape municipal budgets throughout Central Ohio. Because Ohio municipal income taxes are tied to employee work locations, suburban communities that previously banked on steadily compounding payroll withholdings are recalibrating infrastructure programs to adjust to altered commuting habits and commercial office occupancy.
Previously, Pique reported on Oct. 2 that Worthington approved a conditional use permit for a vocational school along Wilson Bridge Road while balancing commercial vacancies against local tax yields (Worthington Approves Ross Medical Education Center for Wilson Bridge Road Space), and reported on Oct. 6 that Gahanna elected officials debated compensation against municipal affordability and flat revenue projections (Gahanna Mayor Resists Proposed Salary Increase as Council Weighs Stagnant Pay).
Gahanna Trims Projections and Delays Creekside
Senior Director of Operations Kevin Schultz outlined the capital outlook during a Sept. 28 Committee of the Whole meeting, explaining that Finance Director Joann Bury lowered the assumed annual income tax growth rate to 2% based on collections through 2026 and return-to-work changes.
While the draft 2027 capital budget requests approximately $22.1 million across city functions—led by $9.2 million for transportation and mobility improvements and $5.1 million for utility systems—the lower revenue trajectory forced immediate trade-offs, Schultz announced.
The most prominent casualty is the Creekside flood mitigation and plaza improvement project, a planned overhaul of the city's commercial and public gathering core along Big Walnut Creek. The project carries an estimated total cost between $23 million and $24 million, but the draft 2027 capital plan allocates no municipal funds for it next year, Schultz said.
Schultz said administrators are assembling an outside funding package and pursuing $35 million to $45 million in pending grant applications to relieve pressure on local funds. Gahanna staff is scheduled to present City Council with financing alternatives and grant updates for Creekside during the first meetings of January 2027.
Regional Income Tax Pressures Across Central Ohio
Gahanna's budgetary caution mirrors broader vulnerabilities across Franklin County, where municipalities rely heavily on local earnings taxes to back debt service and direct capital outlays.
In neighboring Worthington, municipal records document an acute geographic reliance on traditional corporate employment. A Sept. 10 Worthington Planning Commission review noted that the Wilson Bridge Road commercial corridor generates 52% of all municipal income tax collections, even as city officials grapple with persistent multi-year office vacancies in 1970s-era office parks following changes in corporate tenant footprints.
In Columbus, where downtown office attendance remains below pre-2020 levels, council members have exercised stricter scrutiny over specialized reserves. On Sept. 14, Columbus City Council referred Ordinance 2243-2026 back to committee rather than granting emergency passage, halting a proposed $1 million withdrawal from the city's Income Tax Set Aside Subfund for crisis response costs.
Next Steps for Gahanna's Capital Program
Gahanna's capital framework faces formal review across multiple municipal bodies throughout October and November.
The city's CIP Advisory Committee meets on Tuesday, Oct. 6, to review the project rankings and five-year allocations, Schultz announced. The Committee of the Whole is scheduled to examine project priorities and legislative details on Monday, Oct. 12, ahead of a scheduled second reading and adoption vote on ORD-0038-2026 on Monday, Oct. 19.
Adoption of the Capital Improvement Plan establishes multi-year priorities but does not formally appropriate dollars for the upcoming year. Gahanna City Council is scheduled to convene a dedicated municipal budget workshop on Monday, Nov. 2, to evaluate the combined 2027 operating and capital budgets before enacting final appropriations.
How we know this
The sources and records behind this story, with the facts they support.
Supporting evidence (1)
The downgrade, incorporated into Ordinance ORD-0038-2026 introduced on first reading on Oct. 5, eliminates an estimated $3.6 million in anticipated revenue across income-tax-supported municipal accounts over the planning cycle, according to administrative presentations.
Read supporting passage
ORD-0038-2026 · AN ORDINANCE ADOPTING THE 2027-2031 CITY OF GAHANNA CAPITAL IMPROVEMENT PLAN, SUPERSEDING ALL PRIOR CAPITAL IMPROVEMENT PLANS, AND PROVIDING FOR FUTURE SUNSET
Worthington Approves Ross Medical Education Center for Wilson Bridge Road Space
Supporting evidence (1)
Previously, Pique reported on Oct. 2 that Worthington approved a conditional use permit for a vocational school along Wilson Bridge Road while balancing commercial vacancies against local tax yields (Worthington Approves Ross Medical Education Center for Wilson Bridge Road Space), and reported on Oct. 6 that Gahanna elected officials debated compensation against municipal affordability and flat revenue projections (Gahanna Mayor Resists Proposed Salary Increase as Council Weighs Stagnant Pay).
Read supporting passage
Worthington Approves Ross Medical Education Center for Wilson Bridge Road Space
Gahanna Mayor Resists Proposed Salary Increase as Council Weighs Stagnant Pay
Supporting evidence (1)
Previously, Pique reported on Oct. 2 that Worthington approved a conditional use permit for a vocational school along Wilson Bridge Road while balancing commercial vacancies against local tax yields (Worthington Approves Ross Medical Education Center for Wilson Bridge Road Space), and reported on Oct. 6 that Gahanna elected officials debated compensation against municipal affordability and flat revenue projections (Gahanna Mayor Resists Proposed Salary Increase as Council Weighs Stagnant Pay).
Read supporting passage
Gahanna Mayor Resists Proposed Salary Increase as Council Weighs Stagnant Pay
Committee of the Whole · 2026-09-28
Supporting evidence (7)
Senior Director of Operations Kevin Schultz outlined the capital outlook during a Sept. 28 Committee of the Whole meeting, explaining that Finance Director Joann Bury lowered the assumed annual income tax growth rate to 2% based on collections through 2026 and return-to-work changes.
Read supporting passage
Senior Director Schultz stated that the draft 2027 capital budget reflected reduced income tax growth projections. He explained that Director Bury reduced the assumed annual income tax growth rate from 4% to 2% based on 2026 performance, including the effects of return-to-work changes. He stated that this reduction lowered projected resources available for capital improvements by approximately $3.6 million across all income-tax-supported funds, including approximately $1.1 million within the Capital Fund.
While the draft 2027 capital budget requests approximately $22.1 million across city functions—led by $9.2 million for transportation and mobility improvements and $5.1 million for utility systems—the lower revenue trajectory forced immediate trade-offs, Schultz announced.
Read supporting passage
Senior Director Schultz stated that the draft 2027 capital budget requested approximately $22.1 million across all project categories. He identified transportation and mobility as the largest category at approximately $9.2 million, including West Johnstown Road improvements, design work for the Stygler Road, Agler Road, and U.S. 62 improvements, and the annual street and sidewalk programs. He identified approximately $5.1 million for sanitary sewer projects, including pump station improvements.
The project carries an estimated total cost between $23 million and $24 million, but the draft 2027 capital plan allocates no municipal funds for it next year, Schultz said.
Read supporting passage
Senior Director Schultz discussed the Creekside flood mitigation and plaza improvements project. He stated that the draft continued to show no 2027 allocation because the City was still developing the funding package, although the slide showed an estimated total project cost of approximately $23 million to $24 million. He stated that staff expected to return to City Council with additional information, likely during one of the first meetings in January 2027.
Gahanna staff is scheduled to present City Council with financing alternatives and grant updates for Creekside during the first meetings of January 2027.
Read supporting passage
Senior Director Schultz discussed the Creekside flood mitigation and plaza improvements project. He stated that the draft continued to show no 2027 allocation because the City was still developing the funding package, although the slide showed an estimated total project cost of approximately $23 million to $24 million. He stated that staff expected to return to City Council with additional information, likely during one of the first meetings in January 2027.
The city's CIP Advisory Committee meets on Tuesday, Oct. 6, to review the project rankings and five-year allocations, Schultz announced.
Read supporting passage
He requested First Reading the following week and stated that the CIP Advisory Committee would meet on October 6, 2026. He stated that the matter would return to Committee of the Whole on October 12, 2026, for more detailed questions and that Second Reading and adoption were anticipated on or around October 19, 2026.
The Committee of the Whole is scheduled to examine project priorities and legislative details on Monday, Oct. 12, ahead of a scheduled second reading and adoption vote on ORD-0038-2026 on Monday, Oct. 19.
Read supporting passage
He requested First Reading the following week and stated that the CIP Advisory Committee would meet on October 6, 2026. He stated that the matter would return to Committee of the Whole on October 12, 2026, for more detailed questions and that Second Reading and adoption were anticipated on or around October 19, 2026.
Gahanna City Council is scheduled to convene a dedicated municipal budget workshop on Monday, Nov. 2, to evaluate the combined 2027 operating and capital budgets before enacting final appropriations.
Read supporting passage
He also identified the November 2, 2026, budget workshop on the schedule and invited questions.
ARB/MPC Minutes · September 10, 2026 · minutes
Supporting evidence (1)
A Sept. 10 Worthington Planning Commission review noted that the Wilson Bridge Road commercial corridor generates 52% of all municipal income tax collections, even as city officials grapple with persistent multi-year office vacancies in 1970s-era office parks following changes in corporate tenant footprints.
Read supporting passage
The Wilson Bridge Rd. Corridor produces 52% of all income revenue collection
Columbus City Council · 2026-09-14
Supporting evidence (1)
On Sept. 14, Columbus City Council referred Ordinance 2243-2026 back to committee rather than granting emergency passage, halting a proposed $1 million withdrawal from the city's Income Tax Set Aside Subfund for crisis response costs.
Read supporting passage
2243-2026 · To authorize the appropriation of $1,000,000.00 from the unappropriated balance in the Income Tax Set Aside (ITSA) Subfund to support crisis response activity costs; and to declare an emergency. ($1,000,000.00)