
Columbus Legislation Sets Action on Tax Incentive Recommendations
Legislation 0252X-2026 carries consent status for Nov. 16 to accept review council recommendations dissolving four agreements and requiring jobs plans for five others.
Columbus legislation 0252X-2026 carries consent status for Nov. 16, 2026, covering 2026 TIRC recommendations. The action addresses commercial tax abatements granted across the city to spur development and job creation.
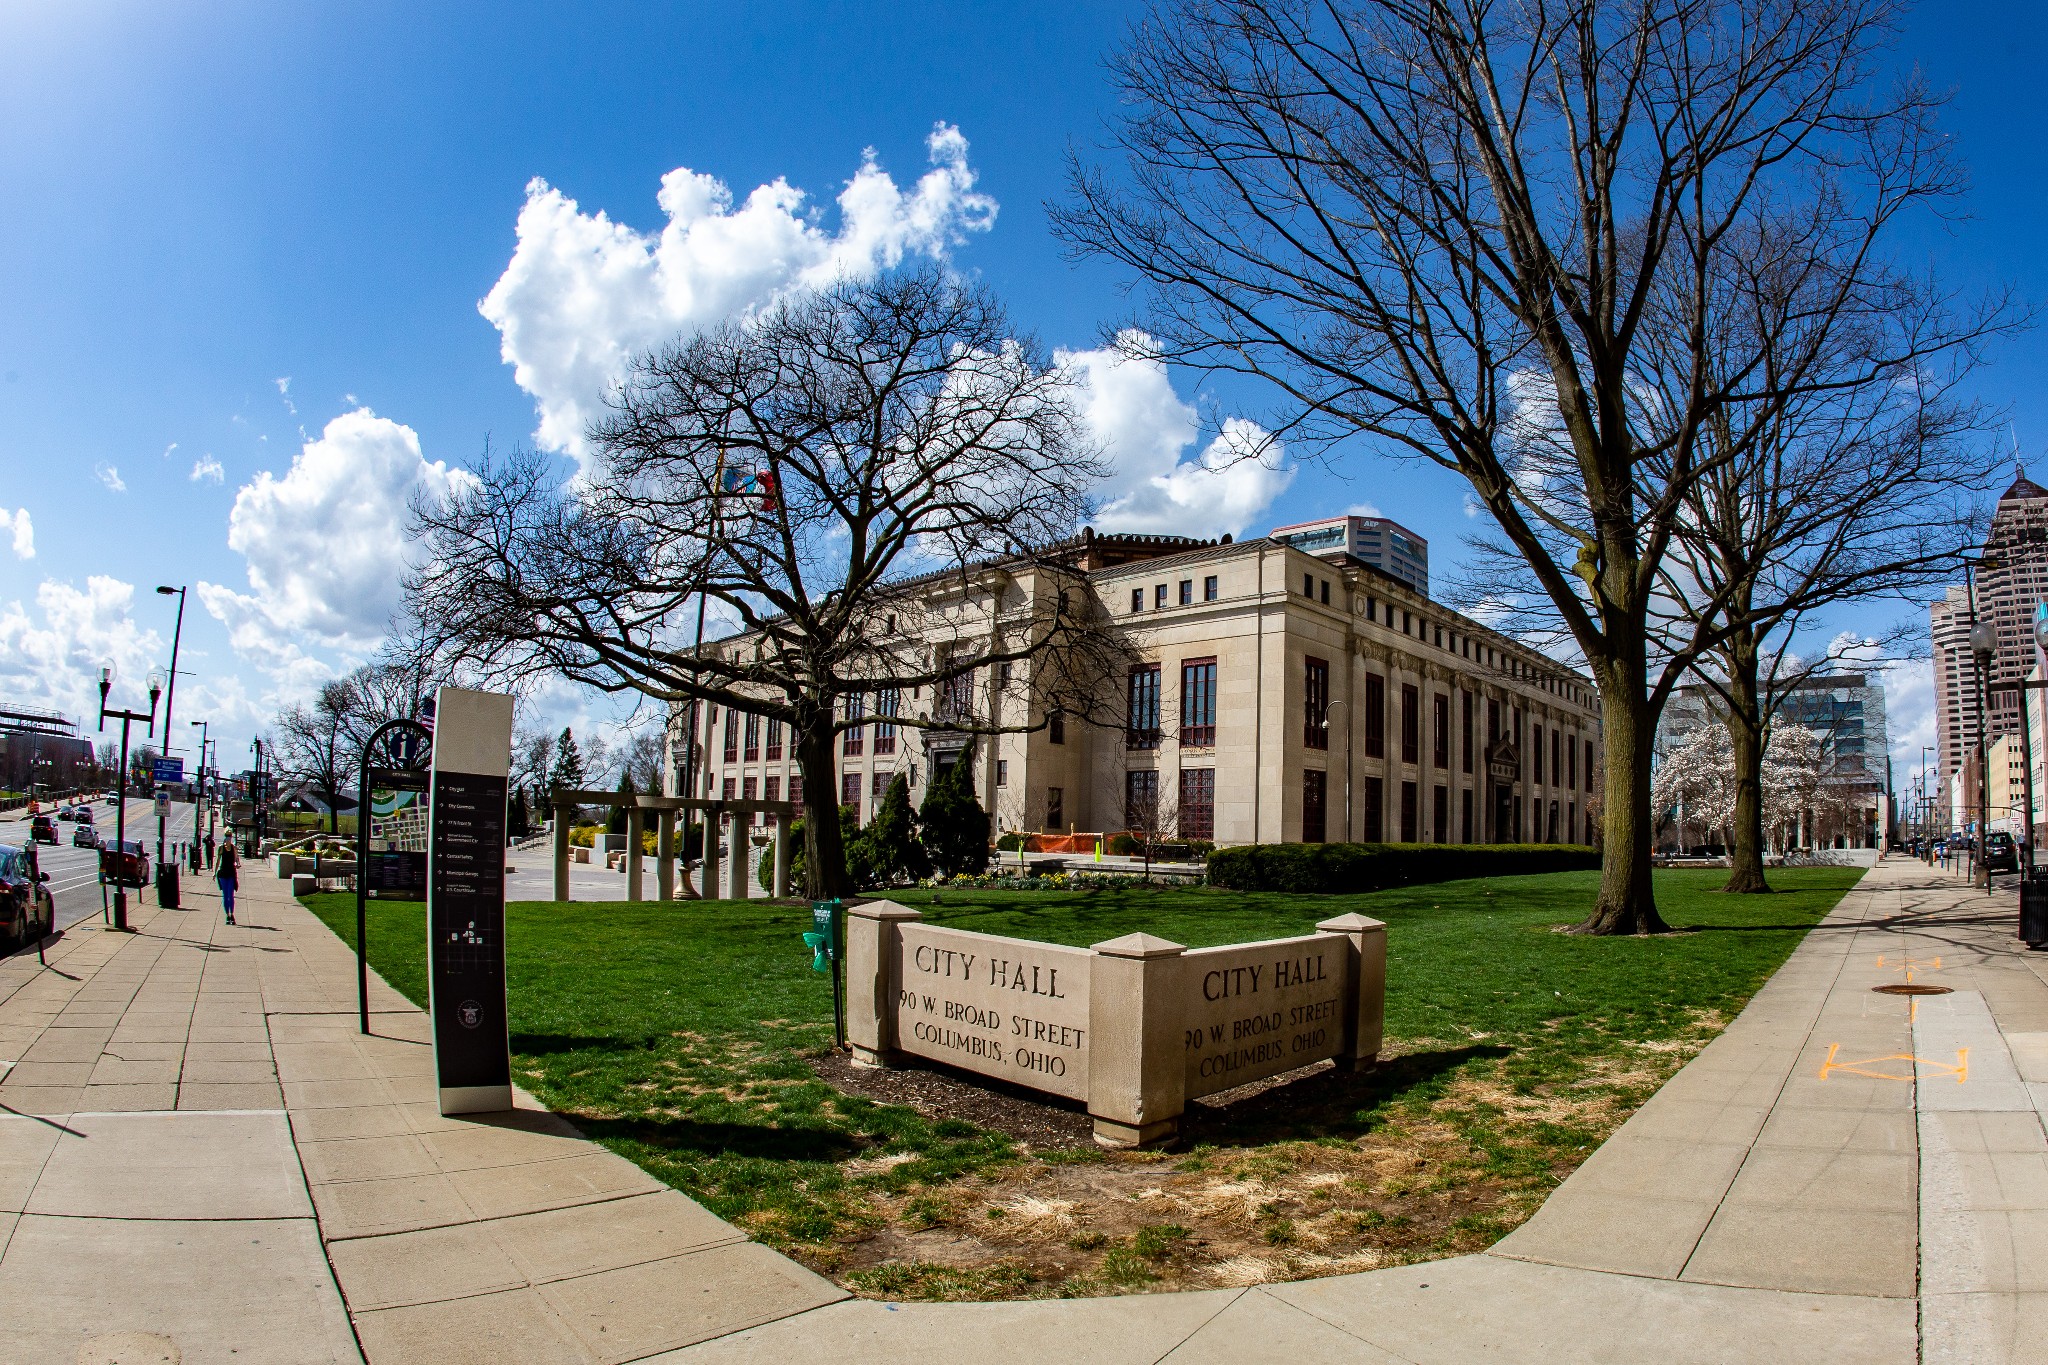
Columbus City Hall at 90 W. Broad Street in downtown Columbus.
Credit: General Ization / Wikimedia Commons Image source
Under state law, the tax incentive review council annually reviews all property tax exemption agreements and required performance reports. The inter-jurisdictional council evaluates whether companies that received property tax exemptions fulfilled their contracted commitments for hiring, payroll, and real property investment.
Four Dissolutions Recommended
In its summary of recommendations, the council recommended dissolving four agreements: EZA 023-17-13, CRA 049-18000-132 17-000, EZA 023-20-11, and EZA 023-19-02. The four contracts comprise three Enterprise Zone agreements and one Community Reinvestment Area agreement where businesses failed to satisfy performance thresholds.
The review council also recommended that five agreements continue conditional on delivering a corrective jobs plan within 60 days: EZA 023-17-12, 023-19-03, 023-18-03, 023-17-05, and 023-19-07. Under the panel's findings, those five companies must submit formal corrective employment strategies within two months or face potential cancellation of their tax abatements.
In other findings from the summary, one Enterprise Zone abatement ends after tax year 2026, while one Community Reinvestment Area agreement must amend targets. The panel also ordered ongoing monitoring for job creation on a third project.
Dissolution Practice and Clawbacks
When Columbus City Council votes to dissolve a property tax abatement, the action terminates the company's ongoing property tax exemption for future tax years. Under long-standing city legislative practice, dissolution returns parcels to standard commercial taxation rather than triggering an automatic clawback of prior tax savings.
In earlier dissolution action, council voted to dissolve an Enterprise Zone agreement with Advanced Turf Solutions, Inc. and ATS Columbus Investments II, LLC, directing the development director to notify tax authorities. In that action, records noted that net new jobs were below the job creation commitment per the agreement. The legislation carried a zero-dollar fiscal note and directed development officials to notify county and state tax authorities of the change, without enacting monetary penalties or retroactive recoupment.
Portfolio Performance Metrics
Despite non-compliance by individual recipients, the city's overall tax incentive portfolio met or exceeded most aggregate targets. According to the summary, the review covered 112 agreements in total: 91 consent, 9 R1, and 13 R2.
The recommendations were transmitted with an Oct. 6 development director memorandum. In that transmittal memorandum, Columbus Development Director Michael H. Stevens reported that across the 112 active agreements, participating companies retained 9,052 jobs, reaching 128 percent of the city's retention goal, and achieved $6.59 billion in real property investment, representing 235 percent of required commitments. Employers reported creating 8,745 net new jobs, or 97 percent of their target, and generated $226.7 million in new-job payroll, or 277 percent of projections. In addition, all 99 municipal tax increment financing districts reviewed by the panel were found in order to continue.
Statutory Deadlines and Meeting Window
The upcoming consent agenda vote also highlights statutory scheduling rules governing municipal tax incentive reviews under Ohio law.
State law mandates that the council submit written recommendations for continuation, modification, or cancellation to the legislative authority by Sept. 1 of each year. Under Section 5709.85 of the Ohio Revised Code, a legislative authority receiving those recommendations must convene and vote within 60 days to accept, reject, or modify them.
The review council met and adopted its recommendations on Aug. 21, 2026. Director Stevens issued his transmittal memorandum to council on Oct. 6, 2026, and council's vote is scheduled for Nov. 16, 2026. That scheduled vote date falls 41 days after the director's formal memorandum, but 87 days after the review council's August determinations. Pique Media submitted an interview inquiry to the Columbus Department of Development regarding how the city measures the 60-day window between the review council's recommendations and council action.
How we know this
The sources and records behind this story, with the facts they support.
Supporting evidence (1)
Columbus legislation 0252X-2026 carries consent status for Nov. 16, 2026, covering 2026 TIRC recommendations.
Read supporting passage
Columbus legislation 0252X-2026 (2026 TIRC Recommendations RY2025): Consent status, agenda date Nov 16, 2026
https://codes.ohio.gov/ohio-revised-code/section-5709.85
Supporting evidence (3)
Under state law, the tax incentive review council annually reviews all property tax exemption agreements and required performance reports.
Read supporting passage
Annually, the tax incentive review council shall review all agreements granting exemptions from property taxation under Chapter 725. or 1728. or under section 3735.671, 5709.28, 5709.62, 5709.63, or 5709.632 of the Revised Code, and any performance or audit reports required to be submitted pursuant to those agreements.
State law mandates that the council submit written recommendations for continuation, modification, or cancellation to the legislative authority by Sept. 1 of each year.
Read supporting passage
On the basis of the determinations, on or before the first day of September of each year, the council shall submit to the legislative authority written recommendations for continuation, modification, or cancellation of each agreement.
Under Section 5709.85 of the Ohio Revised Code, a legislative authority receiving those recommendations must convene and vote within 60 days to accept, reject, or modify them.
Read supporting passage
A legislative authority that receives from a tax incentive review council written recommendations under division (C)(1) or (D) of this section shall, within sixty days after receipt, hold a meeting and vote to accept, reject, or modify all or any portion of the recommendations.
Supporting evidence (6)
In its summary of recommendations, the council recommended dissolving four agreements: EZA 023-17-13, CRA 049-18000-132 17-000, EZA 023-20-11, and EZA 023-19-02.
Read supporting passage
Four agreements are recommended to dissolve: EZA 023-17-13, CRA 049-18000-132 17-000, EZA 023-20-11, and EZA 023-19-02.
The review council also recommended that five agreements continue conditional on delivering a corrective jobs plan within 60 days: EZA 023-17-12, 023-19-03, 023-18-03, 023-17-05, and 023-19-07.
Read supporting passage
Five continue but must deliver a jobs plan within 60 days: EZA 023-17-12, 023-19-03, 023-18-03, 023-17-05, and 023-19-07.
In other findings from the summary, one Enterprise Zone abatement ends after tax year 2026, while one Community Reinvestment Area agreement must amend targets.
Read supporting passage
EZA 023-18-04's abatement ends after TY2026.
In other findings from the summary, one Enterprise Zone abatement ends after tax year 2026, while one Community Reinvestment Area agreement must amend targets.
Read supporting passage
CRA 049-18000-14 17-000 must amend its targets.
According to the summary, the review covered 112 agreements in total: 91 consent, 9 R1, and 13 R2.
Read supporting passage
In total, 112 agreements were reviewed: 91 consent, 9 R1, and 13 R2.
The recommendations were transmitted with an Oct. 6 development director memorandum.
Read supporting passage
Director memo dated Oct 6, 2026: https://legistar3.granicus.com/Columbus/attachments/242d4b22-58f9-443a-abac-4ee2b74ff925.docx
Supporting evidence (2)
In earlier dissolution action, council voted to dissolve an Enterprise Zone agreement with Advanced Turf Solutions, Inc. and ATS Columbus Investments II, LLC, directing the development director to notify tax authorities.
Read supporting passage
To dissolve the Enterprise Zone Agreement with Advanced Turf Solutions, Inc. and ATS Columbus Investments II, LLC (collectively, referred to as “ENTERPRISE”), and to direct the Director of the Department of Development to notify, as necessary, the local and state tax authorities of the dissolution. ($0.00)
In that action, records noted that net new jobs were below the job creation commitment per the agreement.
Read supporting passage
The TIRC, noted from the annual report, that the net new jobs were below the job creation commitment per the AGREEMENT