
Columbus Council Scheduled to Vote on Year-End Budget Transfers Tied to Reserve Shift
Monday's emergency third-quarter balancing package depends on shifting $10 million in recycling and homelessness contract costs into the city's income tax reserve.
Columbus City Council is scheduled to vote at 5 p.m. on Monday, Nov. 16, on an emergency third-quarter budget measure carrying a clerk amendment request. Under the balancing ordinance, those transfers and appropriations are contingent upon passage of a companion $10 million ordinance moving funds from the General Fund into the Income Tax Set Aside subfund.
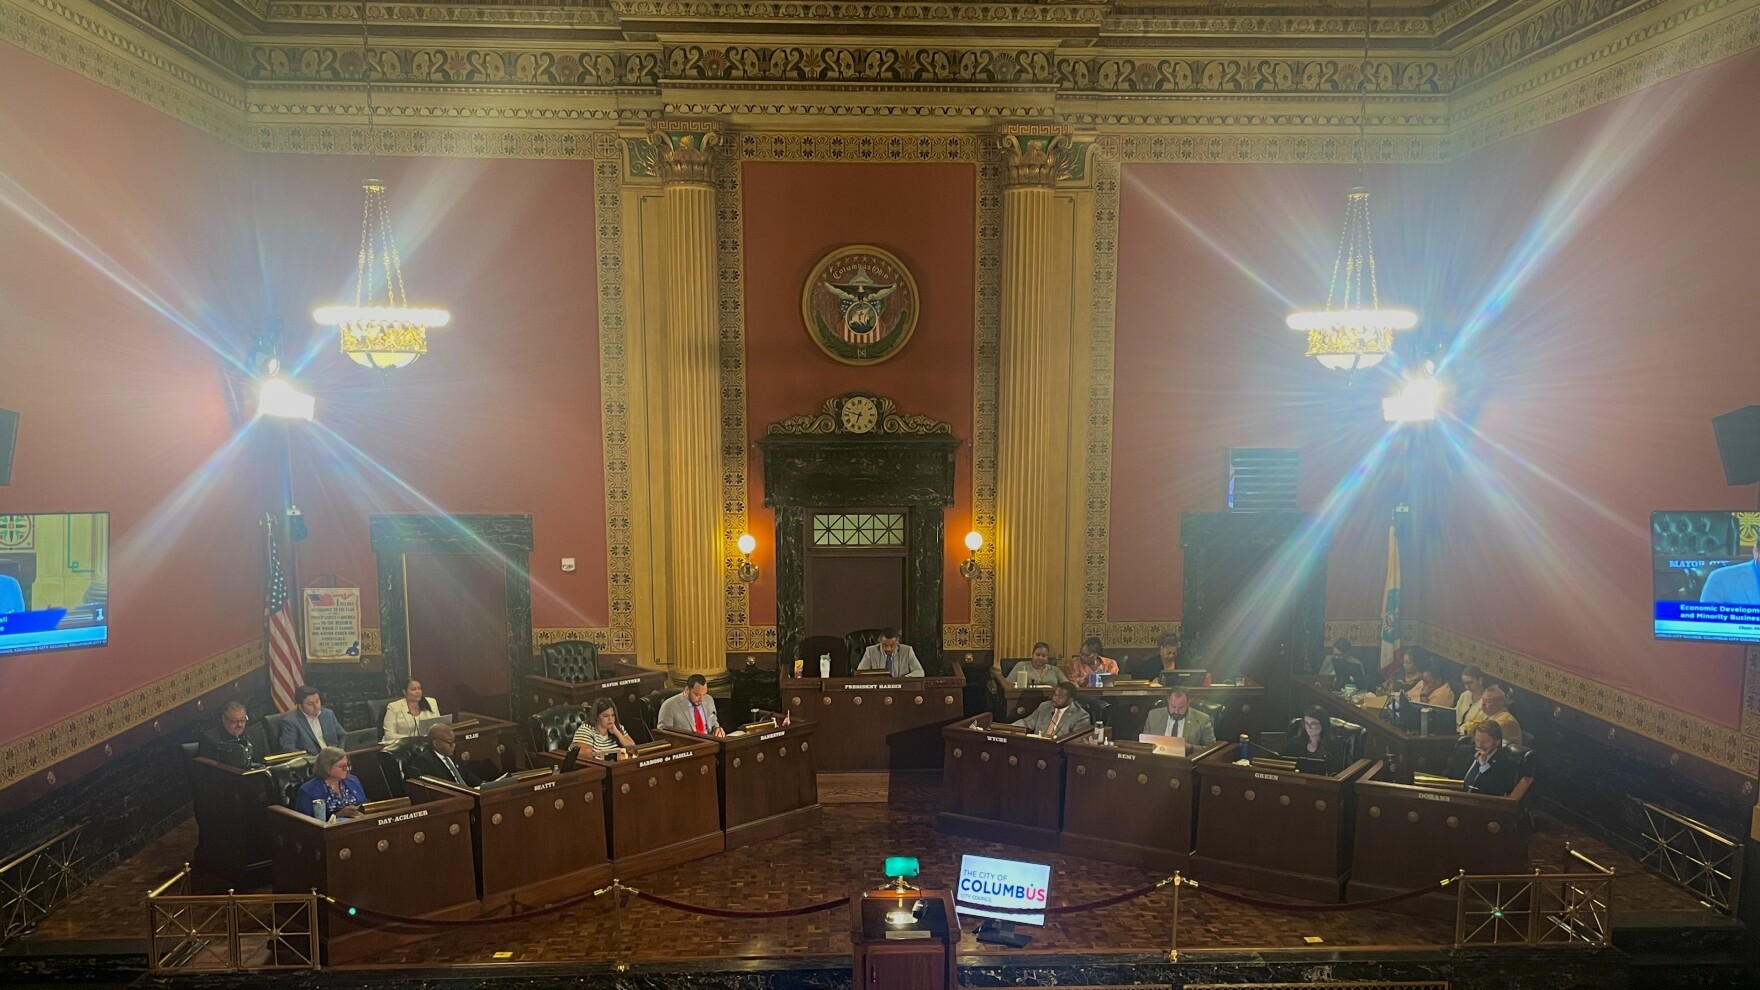
Columbus City Council members meet inside City Council Chambers at Columbus City Hall on July 21, 2025.
Credit: WOSU Public Media Image source
How the year-end transfers and reserve shift work
Following its 2026 third-quarter financial review, the Department of Finance and Management identified surpluses and deficits in several divisions, and the third-quarter ordinance authorizes $29,091,182 in transfers within the General Fund to keep divisions operating without interruption through the end of 2026. The ordinance also authorizes $8 million in new General Fund appropriations tied to a revised City Auditor revenue estimate.
Outside the General Fund, the measure authorizes $1,442,116 in non-General Fund transfers, split between $730,116 within Fleet Management Services and $712,000 within Recreation and Parks. It also transfers $600,000 from Finance Citywide to the Property Management fund, appropriates $600,000 within Property Management, and appropriates $180,000 within the Print and Mail Services fund.
The companion $10 million Income Tax Set Aside ordinance authorizes an expenditure correction moving $10 million from the General Fund into the subfund. According to legislative records, the shift covers partial costs for Rumpke recycling and yard waste contracts and Community Shelter Board homelessness programs—including Continuum of Care, crisis response, outreach, permanent supportive housing and the Safety Net Program—to fund basic city services through the rest of 2026.
Both the $8 million General Fund appropriation and the $10 million Income Tax Set Aside appropriation rely on attached accounting codes, while the General Fund transfer and appropriation ordinance carries a clerk amendment request. Neither the clerk-submitted amendment text listed on the final revised agenda nor the underlying transfer schedules—including the dollar split between Rumpke and the Community Shelter Board or individual division-level General Fund shifts—are publicly readable on Columbus's legislative portal ahead of the 5 p.m. meeting.
Overtime pressures and the reserve-cap clash
On Nov. 12, Mayor Andrew Ginther proposed a $1.3 billion 2027 operating budget as Columbus was projected to go over budget on 2026 police and fire overtime by at least $23 million, according to The Columbus Dispatch. At the same time, Ginther announced he will not sign reserve-cap legislation that council passed 8-0 on Nov. 2, though the measure still takes effect without his signature; he said the restriction left roughly $5 million unavailable for operating costs this budget cycle and argued council was "choosing to tie our hands."
Introduced by Council President Shannon Hardin, who is challenging Ginther in the 2027 election, and supported by City Auditor Jacquelin Lewis to protect the city's credit rating, the code change restricts how much the operating budget can pull from the city's debt services fund. Starting Jan. 1, 2027, the category covering any other non-personnel expenses under the code amendment cannot exceed 90 percent of the prior fiscal year's expenses and encumbrances in that category and must drop by an additional 10 percent each year thereafter. The ordinance directs the Department of Finance and Management, in consultation with the City Auditor, to categorize expenses incurred within the subfund since Jan. 1, 2026.
Previously, Pique Media reported on council's reserve spending cap on Nov. 4 and covered Ginther's 2027 budget proposal on Nov. 12.
Pique’s reporting on the same events, newest first.
South Side Latest
Columbus City Council questions reported South High Street camp clearance
Broadcast reports cite a Dec. 1 vacate deadline for more than 60 residents as council members seek emergency shelter plans.
Columbus
Columbus Authorizes $29.1M Year-End General Fund Budget Transfers
The emergency legislation aligns departmental appropriations with projected expenditures, adds $8 million in General Fund revenue and funds neighborhood initiatives.
Columbus
Columbus Authorizes $10M Shift of Service Costs to Income Tax Reserve
The emergency measure shifts $10 million from the General Fund to the Income Tax Set Aside subfund for recycling and shelter costs.
Columbus
Columbus Advances $400,000 Power Division Waste and Spill Cleanup Bill
Ordinance 3040-2026 moved past first reading Nov. 16 to shift $400,000 within the Electricity Operating Fund—roughly 4.7 times the Division of Power's 2025 waste cleanup spending.
Columbus
Columbus City Council to Vote on $1 Million One Columbus Grant Flagged for Amendment
Monday's Final Revised agenda lists "Request to Amend as Submitted to the Clerk" ahead of the 5 p.m. vote, while the public legislative file remains at Version 1.
Columbus You are reading
Columbus Council Scheduled to Vote on Year-End Budget Transfers Tied to Reserve Shift
Columbus
Mayor Andrew Ginther Proposes $1.3 Billion Columbus Operating Budget Amid Council Feud
The 2027 proposal expands firefighter and police recruitment while cutting funding for health centers serving uninsured residents.
Columbus
Columbus City Council Caps Operating Spending From Income Tax Reserve
The amended legislation establishes a ceiling on operating expenses from the reserve to protect debt service and the city's credit rating.
Columbus
Columbus City Council Moves to Cap Operational Spending From Income Tax Reserve
The legislation would limit operational withdrawals to 90 percent of prior-year levels to safeguard credit ratings and capital borrowing capacity.
How we know this
The sources and records behind this story, with the facts they support.
Supporting evidence (2)
Columbus City Council is scheduled to vote at 5 p.m. on Monday, Nov. 16, on an emergency third-quarter budget measure carrying a clerk amendment request.
Read supporting passage
5:00 PM
Columbus City Council is scheduled to vote at 5 p.m. on Monday, Nov. 16, on an emergency third-quarter budget measure carrying a clerk amendment request.
Read supporting passage
Monday, November 16, 2026
Columbus City Council · 2026-11-16
Supporting evidence (4)
Columbus City Council is scheduled to vote at 5 p.m. on Monday, Nov. 16, on an emergency third-quarter budget measure carrying a clerk amendment request.
Read supporting passage
3186-2026 · To authorize and direct the City Auditor to provide for the transfer of $29,091,182.00 within the general fund; to transfer $1,442,116.00 in appropriations between objects in certain non-general fund departments and divisions; to authorize transfers between funds of $600,000.00; to authorize an appropriation within the Property Management fund and Mail and Print services fund, to authorize appropriation of $8,000,000 within the general fund; and to declare an emergency ($30,533,298.00). REQUEST TO AMEND AS SUBMITTED TO THE CLERK
Under the balancing ordinance, those transfers and appropriations are contingent upon passage of a companion $10 million ordinance moving funds from the General Fund into the Income Tax Set Aside subfund.
Read supporting passage
3031-2026 · To authorize the appropriation of $10,000,000.00 in the General Fund Income Tax Set Aside (ITSA) Subfund; to authorize an expenditure correction in the amount of $10,000,000.00 from the general fund to the General Fund ITSA Subfund; and to declare an emergency. ($10,000,000.00)
The companion $10 million Income Tax Set Aside ordinance authorizes an expenditure correction moving $10 million from the General Fund into the subfund.
Read supporting passage
3031-2026 · To authorize the appropriation of $10,000,000.00 in the General Fund Income Tax Set Aside (ITSA) Subfund; to authorize an expenditure correction in the amount of $10,000,000.00 from the general fund to the General Fund ITSA Subfund; and to declare an emergency. ($10,000,000.00)
Both the $8 million General Fund appropriation and the $10 million Income Tax Set Aside appropriation rely on attached accounting codes, while the General Fund transfer and appropriation ordinance carries a clerk amendment request.
Read supporting passage
3186-2026 · To authorize and direct the City Auditor to provide for the transfer of $29,091,182.00 within the general fund; to transfer $1,442,116.00 in appropriations between objects in certain non-general fund departments and divisions; to authorize transfers between funds of $600,000.00; to authorize an appropriation within the Property Management fund and Mail and Print services fund, to authorize appropriation of $8,000,000 within the general fund; and to declare an emergency ($30,533,298.00). REQUEST TO AMEND AS SUBMITTED TO THE CLERK
Supporting evidence (11)
Under the balancing ordinance, those transfers and appropriations are contingent upon passage of a companion $10 million ordinance moving funds from the General Fund into the Income Tax Set Aside subfund.
Read supporting passage
This ordinance authorizes the transfer funds between objects, divisions and funds in order to allow divisions to continue to operate through the end of 2026. Additional appropriation is being authorized for the general fund due to the revised revenue estimate of the City Auditor. This ordinance is contingent upon the passage of Ordinance 3031-2026.
Following its 2026 third-quarter financial review, the Department of Finance and Management identified surpluses and deficits in several divisions, and the third-quarter ordinance authorizes $29,091,182 in transfers within the General Fund to keep divisions operating without interruption through the end of 2026.
Read supporting passage
As part of the 2026 third quarter financial review, the Department of Finance and Management identified surpluses and deficits in various object classes in several divisions. In order to properly align appropriations with projected expenditures and allow divisions to operate without interruption through the end of 2026, it is necessary to transfer $29,091,182.00 among divisions within the general fund and $1,442,116.00 in certain non-general fund departments and divisions.
The ordinance also authorizes $8 million in new General Fund appropriations tied to a revised City Auditor revenue estimate.
Read supporting passage
SECTION 1. That the Auditor is hereby authorized and directed to appropriate $8,000,000.00 within the General Fund, fund 1000, subfund 100010 per the accounting codes in the attachment to this ordinance.
The ordinance also authorizes $8 million in new General Fund appropriations tied to a revised City Auditor revenue estimate.
Read supporting passage
This ordinance authorizes the transfer funds between objects, divisions and funds in order to allow divisions to continue to operate through the end of 2026. Additional appropriation is being authorized for the general fund due to the revised revenue estimate of the City Auditor. This ordinance is contingent upon the passage of Ordinance 3031-2026.
Outside the General Fund, the measure authorizes $1,442,116 in non-General Fund transfers, split between $730,116 within Fleet Management Services and $712,000 within Recreation and Parks.
Read supporting passage
As part of the 2026 third quarter financial review, the Department of Finance and Management identified surpluses and deficits in various object classes in several divisions. In order to properly align appropriations with projected expenditures and allow divisions to operate without interruption through the end of 2026, it is necessary to transfer $29,091,182.00 among divisions within the general fund and $1,442,116.00 in certain non-general fund departments and divisions.
Outside the General Fund, the measure authorizes $1,442,116 in non-General Fund transfers, split between $730,116 within Fleet Management Services and $712,000 within Recreation and Parks.
Read supporting passage
That the City Auditor is hereby authorized and directed to transfer appropriations in the amount of $730,116.00 within the Fleet Management Services fund, fund 5200, subfund 520001, according to the account codes in the following:
Outside the General Fund, the measure authorizes $1,442,116 in non-General Fund transfers, split between $730,116 within Fleet Management Services and $712,000 within Recreation and Parks.
Read supporting passage
That the City Auditor is hereby authorized and directed to transfer appropriations in the amount of $712,000.00 within the Recreation and Parks operating fund, fund 2285, according to the account codes in the following:
It also transfers $600,000 from Finance Citywide to the Property Management fund, appropriates $600,000 within Property Management, and appropriates $180,000 within the Print and Mail Services fund.
Read supporting passage
That the Auditor is hereby authorized and directed to transfer $600,000.00 from the Finance Citywide, fund 1000, subfund 100010, to the Property Management fund, fund 2294, subfund 229401 per the accounting codes in the attachment to this ordinance.
It also transfers $600,000 from Finance Citywide to the Property Management fund, appropriates $600,000 within Property Management, and appropriates $180,000 within the Print and Mail Services fund.
Read supporting passage
That the Auditor is hereby authorized and directed to appropriate $600,000.00 within the Property Management fund, fund 2294, subfund 229401 per the accounting codes in the attachment to this ordinance.
It also transfers $600,000 from Finance Citywide to the Property Management fund, appropriates $600,000 within Property Management, and appropriates $180,000 within the Print and Mail Services fund.
Read supporting passage
That the Auditor is hereby authorized and directed to appropriate $180,000.00 within the Print and mail services fund, fund 5517, per the accounting codes in the attachment to this ordinance.
Both the $8 million General Fund appropriation and the $10 million Income Tax Set Aside appropriation rely on attached accounting codes, while the General Fund transfer and appropriation ordinance carries a clerk amendment request.
Read supporting passage
SECTION 1. That the Auditor is hereby authorized and directed to appropriate $8,000,000.00 within the General Fund, fund 1000, subfund 100010 per the accounting codes in the attachment to this ordinance.
Supporting evidence (4)
The companion $10 million Income Tax Set Aside ordinance authorizes an expenditure correction moving $10 million from the General Fund into the subfund.
Read supporting passage
This ordinance authorizes the appropriation of $10,000,000.00 in the General Fund Income Tax Set Aside (ITSA) Subfund 100099 and the expenditure correction in the amount of $10,000,000.00 from the general fund, Fund 1000, Subfund 100010 to the General Fund Income Tax Set Aside Subfund 100099.
According to legislative records, the shift covers partial costs for Rumpke recycling and yard waste contracts and Community Shelter Board homelessness programs—including Continuum of Care, crisis response, outreach, permanent supportive housing and the Safety Net Program—to fund basic city services through the rest of 2026.
Read supporting passage
Expenditure corrections are being requested to cover the partial costs of the following contracts; RUMPKE recycling and yard waste and the Community Shelter Board initiatives (Continuum of Care Application, Crisis Response, Outreach Services, Permanent Supportive Housing (PSH) Services, and the Safety Net Program) addressing homelessness in the City of Columbus.
According to legislative records, the shift covers partial costs for Rumpke recycling and yard waste contracts and Community Shelter Board homelessness programs—including Continuum of Care, crisis response, outreach, permanent supportive housing and the Safety Net Program—to fund basic city services through the rest of 2026.
Read supporting passage
These expenditure corrections and transfers are necessary to provide funding for basic city services for the remainder of 2026.
Both the $8 million General Fund appropriation and the $10 million Income Tax Set Aside appropriation rely on attached accounting codes, while the General Fund transfer and appropriation ordinance carries a clerk amendment request.
Read supporting passage
SECTION 1. That the appropriation of $10,000,000.00 in the General Fund ITSA Subfund is hereby authorized per the accounting codes in the attachment to this ordinance.
https://www.yahoo.com/news/politics/articles/ginther-budget-cuts-health-spending-172558630.html
Supporting evidence (10)
On Nov. 12, Mayor Andrew Ginther proposed a $1.3 billion 2027 operating budget as Columbus was projected to go over budget on 2026 police and fire overtime by at least $23 million, according to The Columbus Dispatch.
Read supporting passage
Columbus Mayor Andrew Ginther proposed his 2027 operating budget at the Linden Community Center on Nov. 12, 2026.
On Nov. 12, Mayor Andrew Ginther proposed a $1.3 billion 2027 operating budget as Columbus was projected to go over budget on 2026 police and fire overtime by at least $23 million, according to The Columbus Dispatch.
Read supporting passage
Ginther's proposed $1.3 billion operating budget would boost firefighter hiring and keep funding stable for the homeless shelters.
On Nov. 12, Mayor Andrew Ginther proposed a $1.3 billion 2027 operating budget as Columbus was projected to go over budget on 2026 police and fire overtime by at least $23 million, according to The Columbus Dispatch.
Read supporting passage
Columbus is projected to go over budget on police and fire overtime in 2026 by at least $23 million.
At the same time, Ginther announced he will not sign reserve-cap legislation that council passed 8-0 on Nov. 2, though the measure still takes effect without his signature; he said the restriction left roughly $5 million unavailable for operating costs this budget cycle and argued council was "choosing to tie our hands."
Read supporting passage
After City Council voted ten days ago to restrict how much the operating budget can pull from the city's debt services fund, Ginther said he will not sign the legislation. It's a rare, symbolic move for Ginther but the legislation will still take effect without his signature.
At the same time, Ginther announced he will not sign reserve-cap legislation that council passed 8-0 on Nov. 2, though the measure still takes effect without his signature; he said the restriction left roughly $5 million unavailable for operating costs this budget cycle and argued council was "choosing to tie our hands."
Read supporting passage
Council voted 8-0 originally for the legislation introduced by Hardin and supported by City Auditor Jacquelin Lewis. Council and Lewis said the code change was a fiscally responsible move aimed at protective the city's perfect credit rating.
At the same time, Ginther announced he will not sign reserve-cap legislation that council passed 8-0 on Nov. 2, though the measure still takes effect without his signature; he said the restriction left roughly $5 million unavailable for operating costs this budget cycle and argued council was "choosing to tie our hands."
Read supporting passage
The impact this budget cycle was about $5 million that could not be used for operating costs, Ginther said.
At the same time, Ginther announced he will not sign reserve-cap legislation that council passed 8-0 on Nov. 2, though the measure still takes effect without his signature; he said the restriction left roughly $5 million unavailable for operating costs this budget cycle and argued council was "choosing to tie our hands."
Read supporting passage
"When Columbus residents need us to step up, City Council is choosing to tie our hands," Ginther said.
Introduced by Council President Shannon Hardin, who is challenging Ginther in the 2027 election, and supported by City Auditor Jacquelin Lewis to protect the city's credit rating, the code change restricts how much the operating budget can pull from the city's debt services fund.
Read supporting passage
The mayor's proposal is the first step in a process that will play out against a feud between Ginther and City Council President Shannon Hardin, who is challenging the mayor in the 2027 election.
Introduced by Council President Shannon Hardin, who is challenging Ginther in the 2027 election, and supported by City Auditor Jacquelin Lewis to protect the city's credit rating, the code change restricts how much the operating budget can pull from the city's debt services fund.
Read supporting passage
Council voted 8-0 originally for the legislation introduced by Hardin and supported by City Auditor Jacquelin Lewis. Council and Lewis said the code change was a fiscally responsible move aimed at protective the city's perfect credit rating.
Introduced by Council President Shannon Hardin, who is challenging Ginther in the 2027 election, and supported by City Auditor Jacquelin Lewis to protect the city's credit rating, the code change restricts how much the operating budget can pull from the city's debt services fund.
Read supporting passage
After City Council voted ten days ago to restrict how much the operating budget can pull from the city's debt services fund, Ginther said he will not sign the legislation. It's a rare, symbolic move for Ginther but the legislation will still take effect without his signature.
Supporting evidence (1)
At the same time, Ginther announced he will not sign reserve-cap legislation that council passed 8-0 on Nov. 2, though the measure still takes effect without his signature; he said the restriction left roughly $5 million unavailable for operating costs this budget cycle and argued council was "choosing to tie our hands."
Read supporting passage
{Body=Columbus City Council, Content type=Outcomes, Document coverage=API text and document metadata; linked PDF bytes are not retained, Local time=5:00 PM, Location=City Council Chambers, Rm 231, Meeting date=2026-11-02T00:00:00, Municipality=columbus}
Supporting evidence (3)
Starting Jan. 1, 2027, the category covering any other non-personnel expenses under the code amendment cannot exceed 90 percent of the prior fiscal year's expenses and encumbrances in that category and must drop by an additional 10 percent each year thereafter.
Read supporting passage
Such expenses shall not be categorized as “any other non-personnel expenses” pursuant to division (E)(2)(j).
Starting Jan. 1, 2027, the category covering any other non-personnel expenses under the code amendment cannot exceed 90 percent of the prior fiscal year's expenses and encumbrances in that category and must drop by an additional 10 percent each year thereafter.
Read supporting passage
Beginning January 1, 2027, those expenses categorized under division (E)(2)(j) cannot exceed ninety (90) percent of the sum total of expenses and encumbrances similarly categorized in the prior fiscal year during the current fiscal year. In each year thereafter, the maximum allowable total expenses shall decrease an additional ten (10) percent from the total determined by the City Auditor under division (F).
The ordinance directs the Department of Finance and Management, in consultation with the City Auditor, to categorize expenses incurred within the subfund since Jan. 1, 2026.
Read supporting passage
It shall be the responsibility of the Department of Finance and Management, in consultation with the City Auditor, to determine the classification of expenses defined in division (E)(2) of this section and categorize expenses incurred within the subfund since January 1, 2026.
Columbus City Council Caps Operating Spending From Income Tax Reserve
Supporting evidence (1)
Previously, Pique Media reported on council's reserve spending cap on Nov. 4 and covered Ginther's 2027 budget proposal on Nov. 12.
Read supporting passage
Columbus City Council Caps Operating Spending From Income Tax Reserve
Mayor Andrew Ginther Proposes $1.3 Billion Columbus Operating Budget Amid Council Feud
Supporting evidence (1)
Previously, Pique Media reported on council's reserve spending cap on Nov. 4 and covered Ginther's 2027 budget proposal on Nov. 12.
Read supporting passage
Mayor Andrew Ginther Proposes $1.3 Billion Columbus Operating Budget Amid Council Feud